Deep Dive Oct 18, 2026
Is GPU compute tight? The answer is in contract length
Key takeaways
CoreWeave, a cloud company that specializes in renting out GPUs, the chips AI runs on, says rental prices rose about 25% starting in July. Yet a public index that compiles listed prices from dozens of providers read only a 5% rise over a year in mid-September. Both numbers can be right: one most likely measures contract prices, the other measures listed prices. The real tightness is in contract length, where customers who won't commit long-term pay about 2.5 to 4 times the long-contract price. CoreWeave's third-quarter results will test this call.
One: Two numbers that disagree
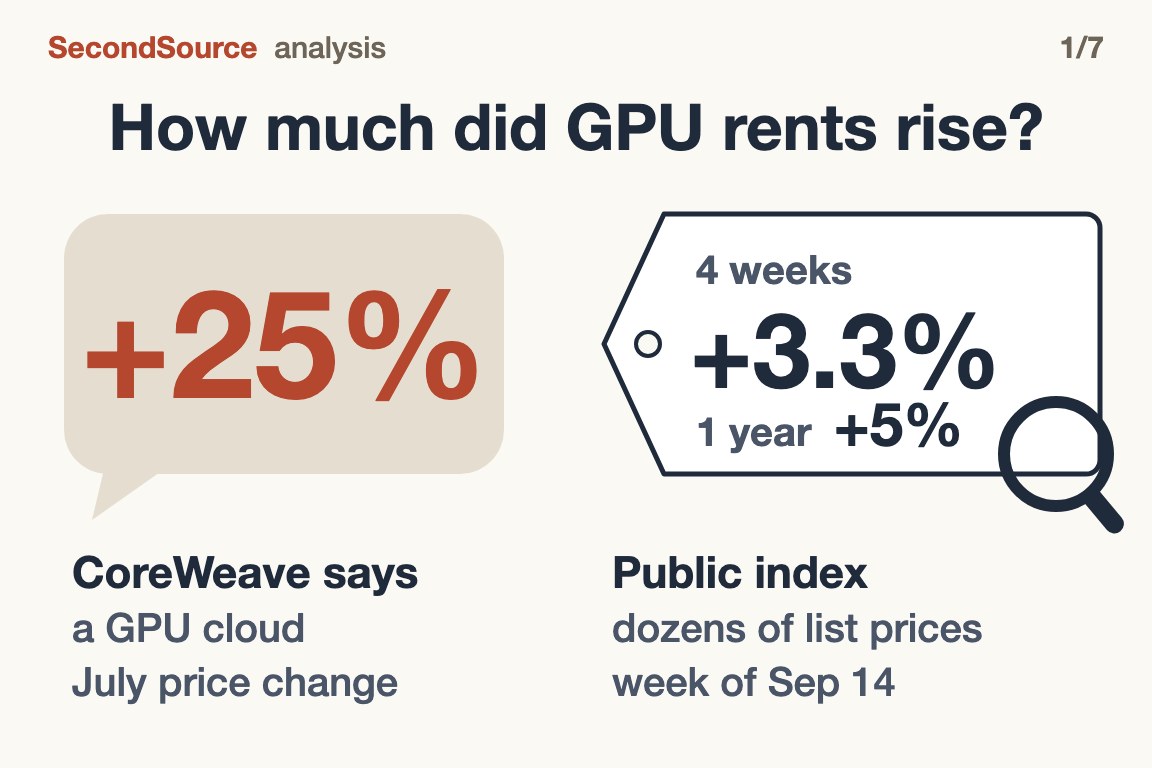
On the August 11 earnings call, CoreWeave CFO Nitin Agrawal described "our July pricing changes which included an approximately 25% increase across SKUs" (call transcript). An SKU is a product model. On September 17 CoreWeave issued US$3 billion of convertible notes, and the attached investor presentation repeated the 25%.
In the same period, getdeploying, a public index that compiles providers' listed prices, read only a 3.3% rise over four weeks and 5% over a year for the week of September 14. SecondSource's September 18 daily brief drew a conclusion from the gap: the tightness is concentrated in newly signed short contracts, out of sight of public prices.
The difference matters because AI companies signing compute contracts, creditors lending to GPU rental companies and investors judging whether AI compute is overbuilt all watch these two kinds of numbers. Reading only one of the two makes the market look too loose or too tight. A month later, this piece rechecks the September call.
Two: One is a contract price, the other a listed price
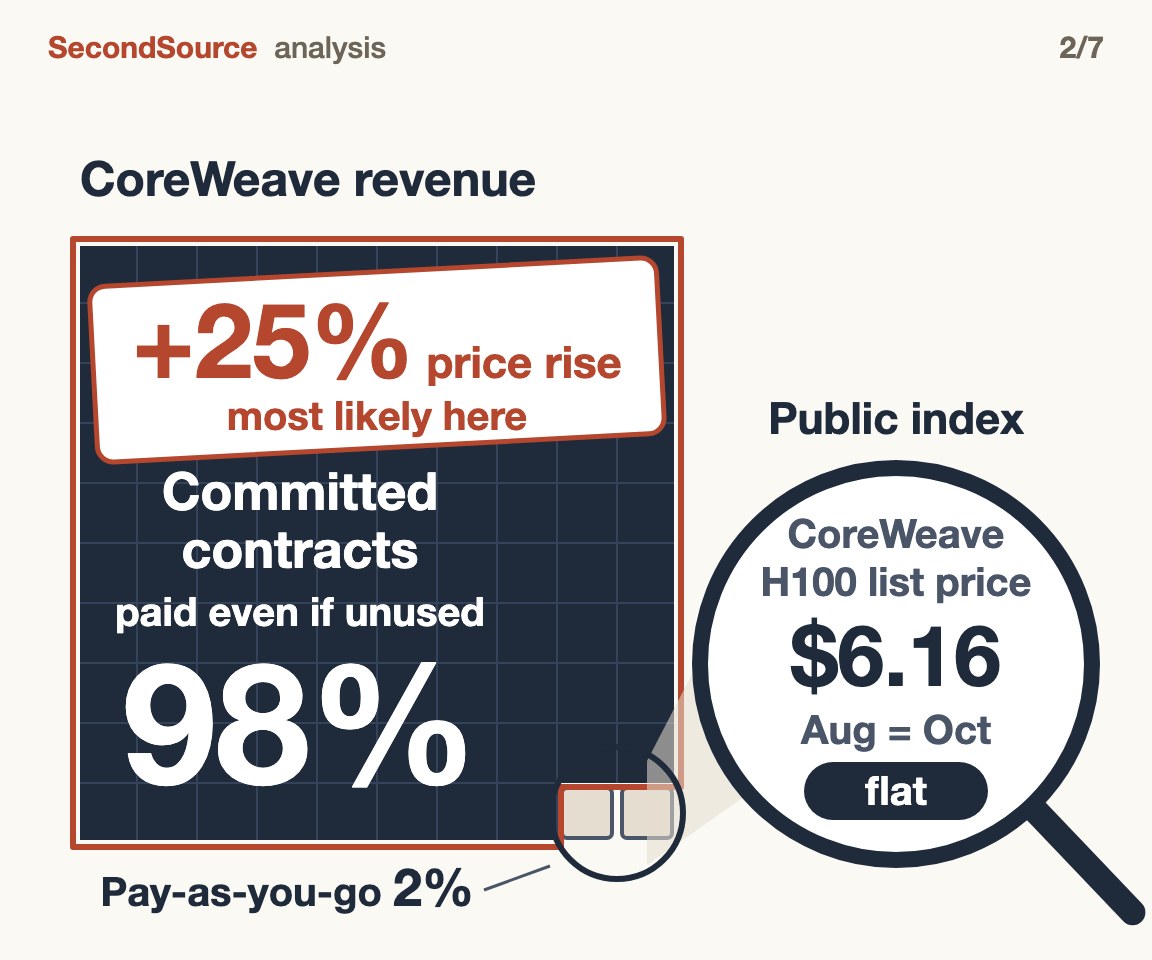
A GPU can be rented in two ways. One is pay-as-you-go: the listed price on a provider's website, billed by the hour and stoppable at any time. The other is a contract price locked in for months or years, mostly under committed contracts that are paid whether or not the capacity is used. Hotels work the same way, with a rack rate posted at the front desk and a rate negotiated in a corporate contract.
CoreWeave's second-quarter 10-Q says 98% of revenue comes from committed contracts and only about 2% from pay-as-you-go. CoreWeave's pricing page lists the H100 at US$6.16 per GPU per hour, the figure read on October 18. The site keeps no older versions to compare against. The October price matches the figure a third-party article cited in August, so no change around July is visible. The public index tracks listed prices only, and in the index CoreWeave appears at that unchanged US$6.16.
Our read: the 25% most likely went into contract prices. The CFO did not say which kind of price the 25% refers to, so this reading rests on the two public documents above. The 25% and the 5% measure two different groups of prices and cannot be compared directly.
Three: The tightness is in contract length
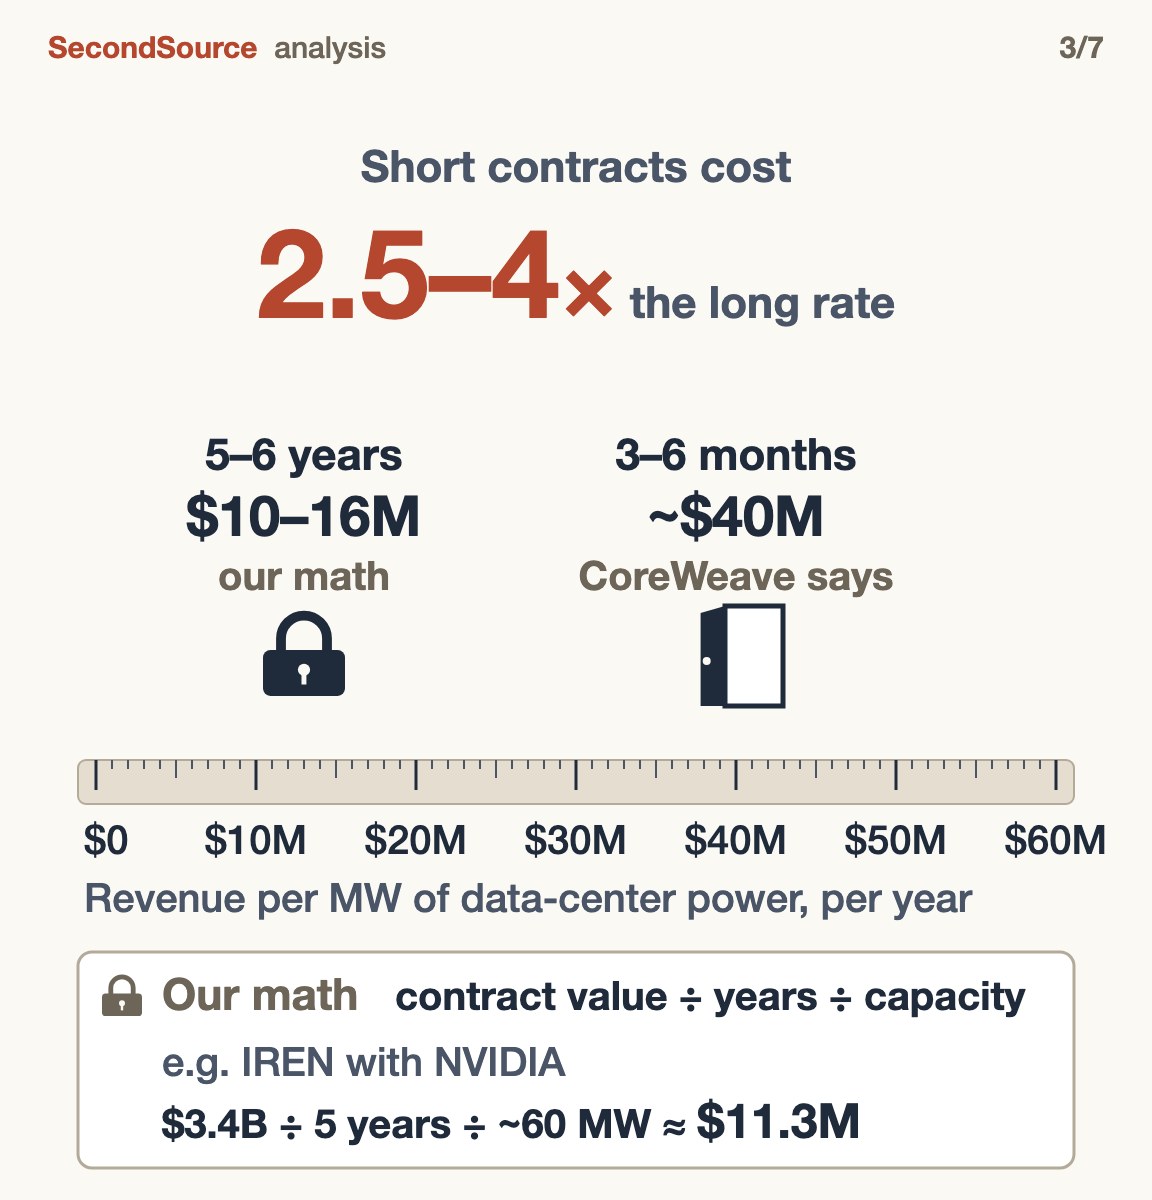
Contract prices also differ widely, depending on how long the contract runs. Contracts come in different sizes, so, as with turning rent into rent per square foot, the comparison uses revenue per MW per year. MW measures a data center's power capacity.
At the shortest end, CoreWeave's presentation puts three-to-six-month contracts signed in the third quarter at about US$40 million per MW per year. At the longest end, SecondSource found five contracts of five to six years with value, term and capacity all public, and divided total value by years and then by capacity. For example, IREN, which rents out GPUs, has a US$3.4 billion, 5-year contract with NVIDIA for about 60 MW, which works out to about US$11.3 million per MW per year. The five contracts together fall between about US$10 million and US$16 million.
US$40 million divided by US$10 million to US$16 million means a short contract costs about 2.5 to 4 times a long one. For the provider, a customer locked in for five years means years of revenue secured in advance, which is worth a discount. A customer who can leave at any time leaves the provider carrying the risk of idle machines, so the unit price is higher. This price gap, together with the long-contract terms in the next section, is the basis for calling the market tight. No earlier year's multiple, calculated the same way, exists for comparison, so how much tighter than usual cannot be said.
Four: Long contracts are cheaper, but the terms are getting tougher
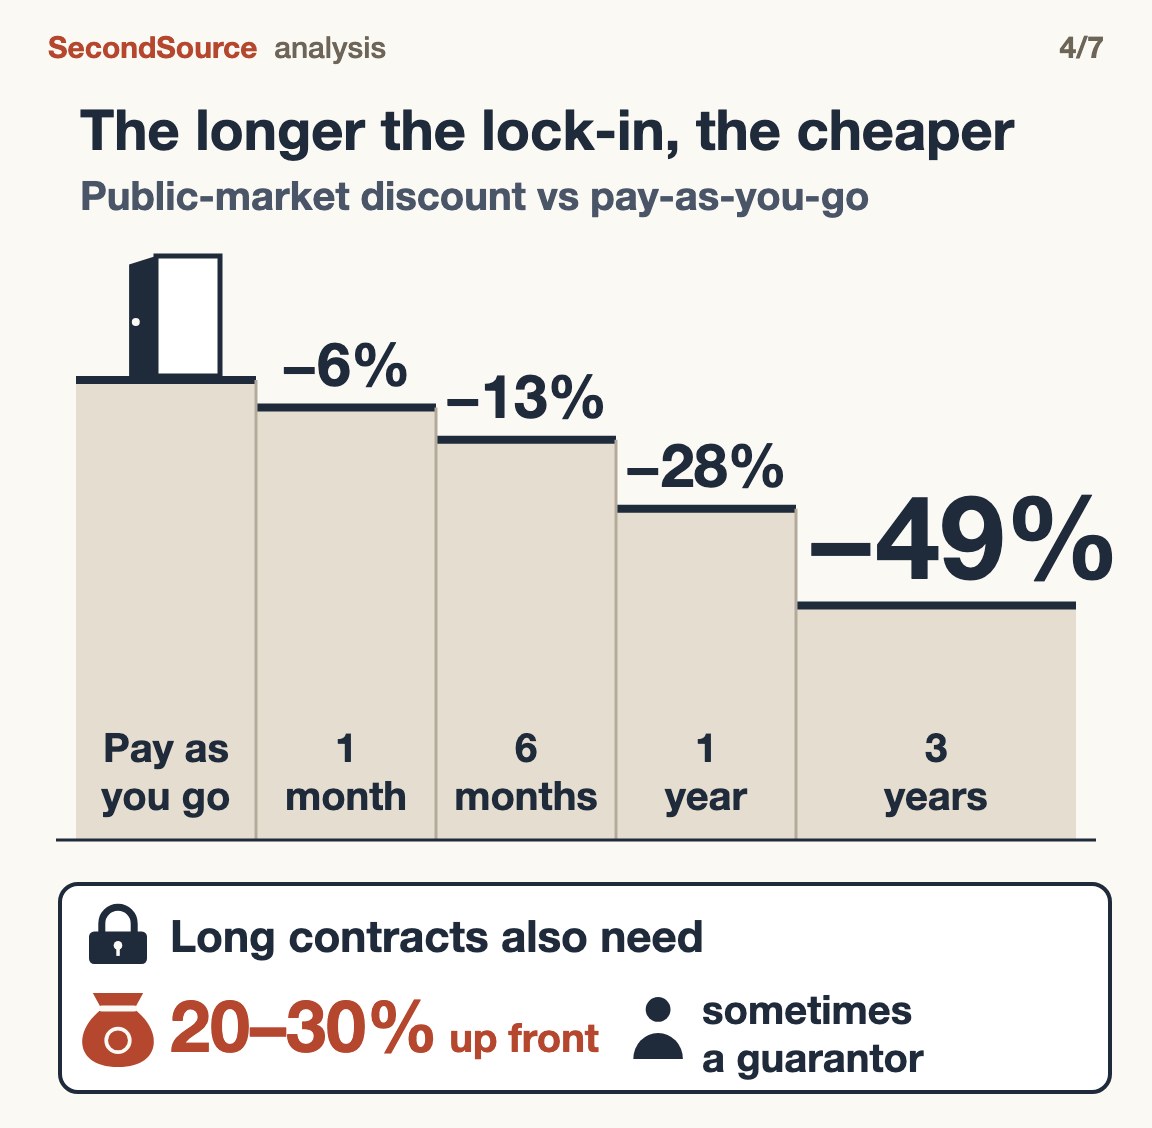
Longer commitments cost less in the public market too. getdeploying's data, measured against pay-as-you-go, shows one month about 6% cheaper, six months about 13%, one year about 28% and three years about 49%.
But the terms on long contracts are getting tougher. SemiAnalysis, a semiconductor research firm, wrote in April that pay-as-you-go capacity for every GPU type was fully rented, and that AI labs were increasingly willing to prepay more than 20% on contracts of four years or more (original). On October 13 the Wall Street Journal, citing SemiAnalysis, reported that cloud providers now require multi-year contracts, often with prepayments as high as 30% and sometimes a guarantor. IREN's contract with Microsoft spells out a 20% prepayment for each tranche.
Five: Why CoreWeave's company-wide average is low
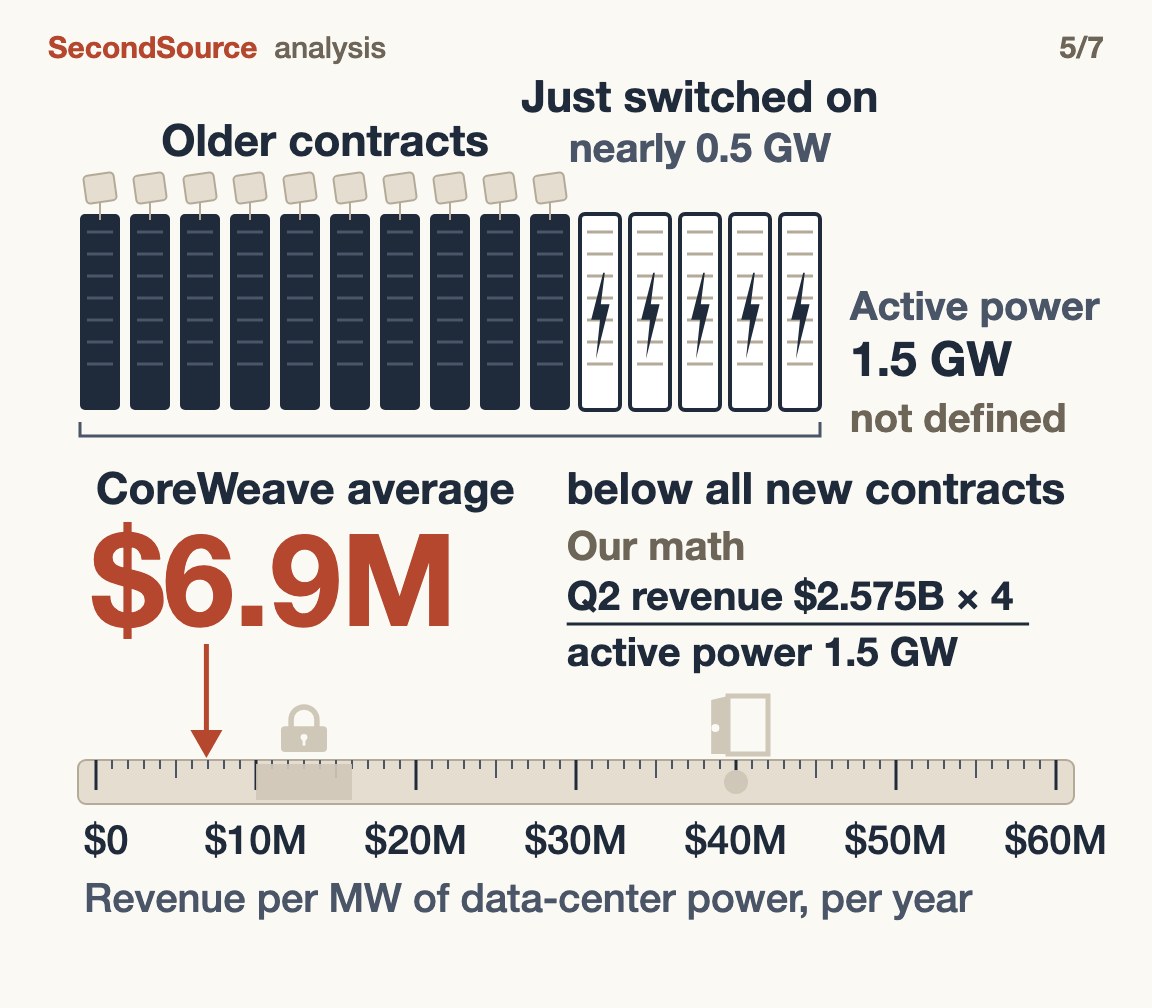
New prices are this high, yet CoreWeave's company-wide average is low. SecondSource multiplied second-quarter revenue of US$2,575 million by four and divided the result by the 1.5 GW of data-center capacity drawing power at quarter end. That gives about US$6.9 million per MW per year, below every newly signed price. CoreWeave's filings call that capacity active power. One GW is 1,000 MW.
The logic is a landlord's average rent: most tenants signed years ago, and new, higher rents count only when old leases expire and renew. The 10-Q doesn't say when each group of contracts expires, but the CFO said the capacity coming up for renewal is a very limited part of the fleet. Two more things pull the average down. Nearly 500 MW was newly connected during the quarter and has not billed for a full quarter. And active power has no definition, so whether active power counts only server power or also cooling is unknown. The available data can't say how much each of the three contributes.
Six: In October, another company's listed prices moved
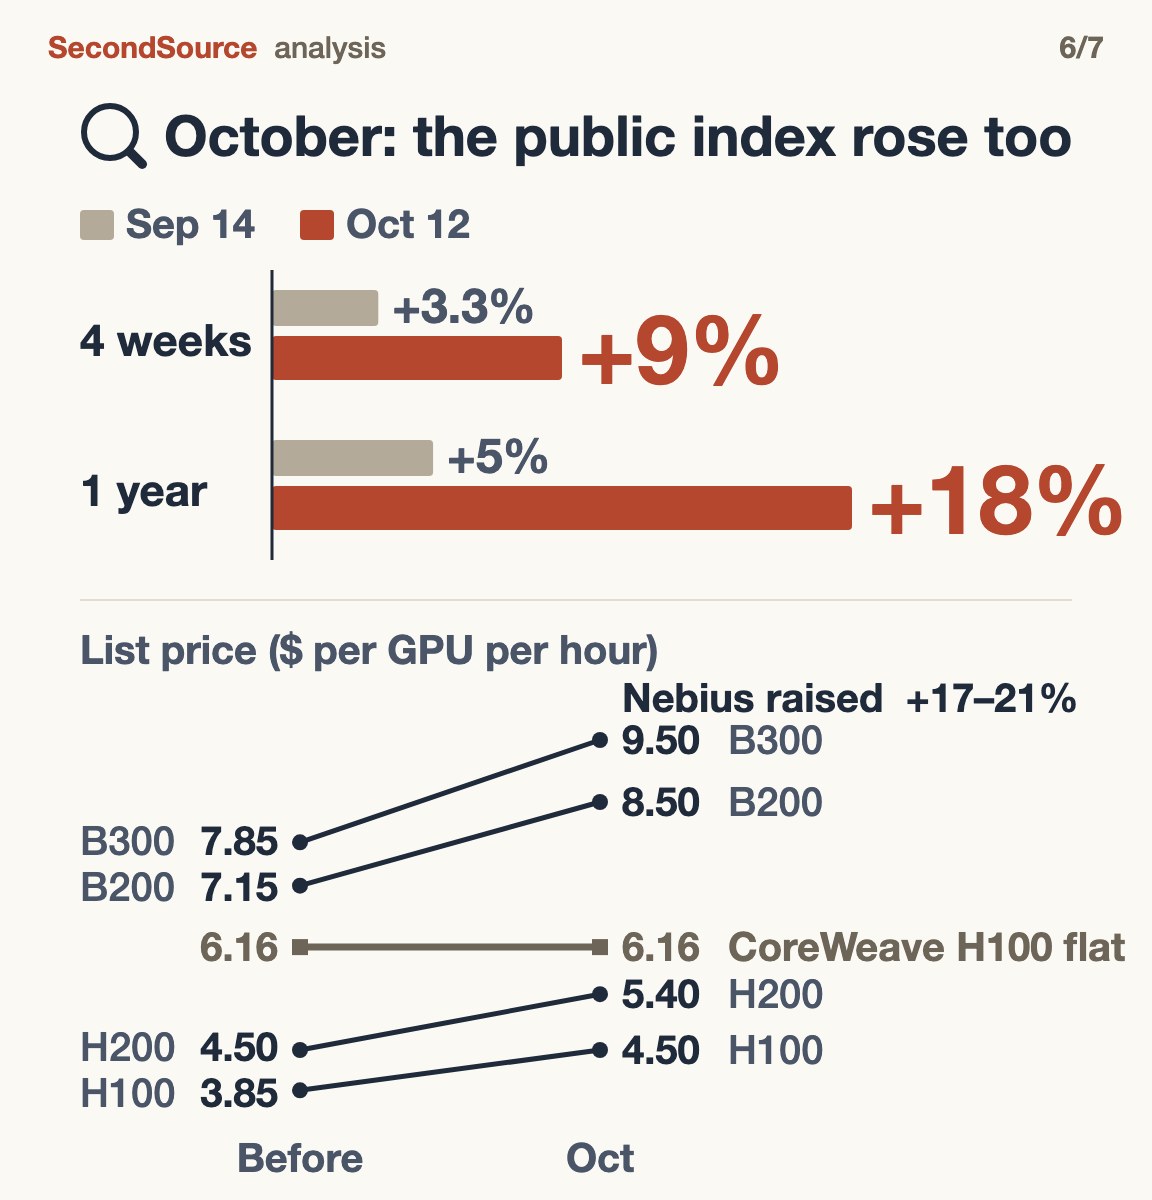
For the week of October 12, getdeploying's reading became 9% over four weeks and 18% over a year, with 21 of 26 GPU models up; SecondSource's recomputation from getdeploying's public weekly data matches. In the same period Nebius, another GPU rental company, raised listed prices from October 1 (Nebius pricing page). The H100 went from US$3.85 to US$4.50 an hour, and the increases across the H100 and three other chips ranged from 17% to 21%. CoreWeave's website still lists the H100 at US$6.16.
So the public index can see price increases, but only the Nebius kind, where listed prices change. Each provider's contribution to the index rise hasn't been broken out.
Seven: What this means for AI compute investment
The world spends upward of a trillion dollars a year on AI compute, and a core question is whether that money comes back. Rental prices that hold up are good news for GPU rental companies that borrowed to build data centers. But new prices reach revenue only as old contracts expire, so payback will be slower than headline rental prices suggest. For AI companies signing compute contracts, the quote depends on contract length, and the public index is useful only for direction.
Eight: The number to watch next
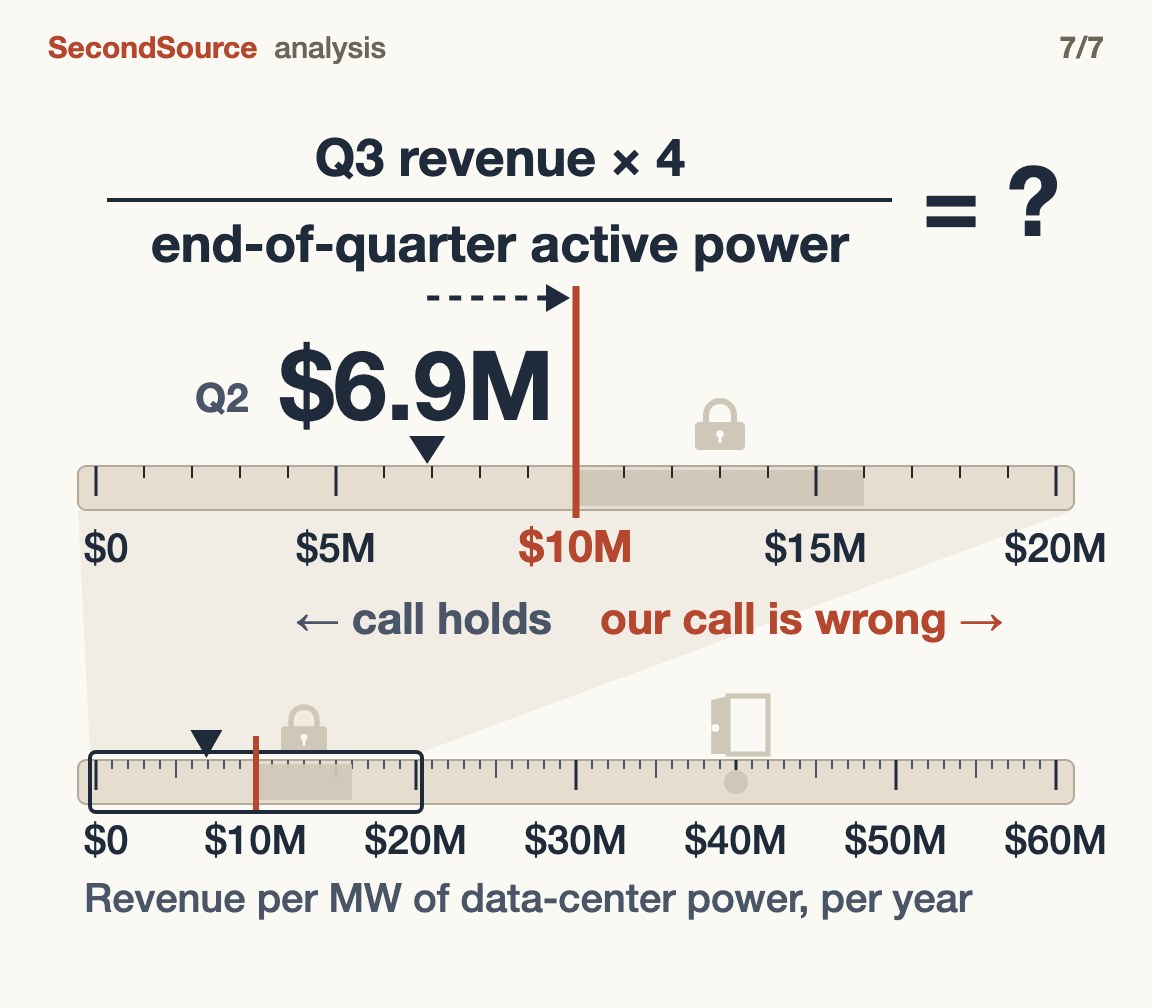
Once CoreWeave's third-quarter earnings press release is out, the company-wide average can be recomputed the same way as in section five. US$10 million is the bottom of the five-year contract price range. Reaching that line would mean the company-wide average has come close to newly signed long-contract prices, and the price increases have spread across the whole company. CoreWeave has not announced the results date.
What would prove this wrong
The deadlines and thresholds below are an observation window set by SecondSource.
1. Within 14 days after CoreWeave's third-quarter earnings press release, that figure crosses the US$10 million line. This piece's reading, "the price increases are concentrated in the newest contracts, and the company-wide average can't catch up in the short run," is withdrawn and replaced by a reading that the whole company is repricing.
2. By December 31, 2026, getdeploying's H100 median, or the H100 index of Silicon Data, a company that publishes GPU rental price indexes, falls 15% or more from the week of October 12, and Nebius or CoreWeave announces a price cut. This piece's "GPU compute is tight" is rewritten as "October was the peak."
3. By December 31, 2026, any GPU rental company discloses a five-year contract at US$20 million per MW per year or more, with value, term and capacity all public. The long-contract price range and the short-to-long multiple are both recalculated.
Appendix: where the numbers come from
For readers who want to check the details: the source and limits of every number in the main text are here.
The two kinds of price side by side.
| Number | What it measures | Compared with | Whose price |
|---|---|---|---|
| CoreWeave up 25% | Prices of new and renewed contracts | Contract prices before July | One company, 98% committed contracts |
| CoreWeave US$40 million per MW per year | A year's revenue from three-to-six-month contracts | Divided by the power needed to serve those contracts | One company's short contracts signed in the third quarter |
| getdeploying +9% over four weeks, +18% over a year | Median listed price for each GPU model | The same model's median four weeks and a year earlier | Pay-as-you-go listed prices from 40 to 88 providers |
| CoreWeave company-wide about US$6.9 million per MW per year | All second-quarter revenue, times four | Divided by active power at quarter end | All of one company's contracts |
The September 18 call said the two numbers were "an order of magnitude" apart, comparing the short-contract US$40 million with a company-wide average of US$7 million to US$8 million. The gap is actually less than ten times.
Prices lined up by contract length.
| Contract | Price, autumn 2026 | Term, and whether the customer can leave early | Source of the figure |
|---|---|---|---|
| Pay-as-you-go listed | H100 median US$3.51 an hour (40 providers); specialist GPU clouds US$4.50; big clouds such as Amazon, Microsoft and Google US$7.89; Silicon Data's specialist-cloud H100 rental index US$2.82 on October 17, +6.4% over seven days | Stop at any time | Third-party compilation of listed prices |
| One-year contract | H100 US$1.70 → US$2.35 an hour (October 2025 to March 2026) | One year | Silicon Data figures cited by SemiAnalysis |
| Three-to-six-month contract | CoreWeave about US$40 million per MW per year, about US$7.6 to US$8.4 per GPU per hour | Three to six months | Company-reported |
| Cancellable big order | Google pays SpaceX US$920 million a month to rent 110,000 GB200s, about US$11.6 per GPU per hour, about US$55 million to US$60 million per MW per year | Three years on paper, cancellable on 90 days' notice | Four outlets report the same figures; unit price estimated by SecondSource |
| Five-to-six-year contract | IREN–NVIDIA about US$11.3 million; IREN–Microsoft about US$9.7 million; Nebius–Microsoft at least US$11.6 million; OpenAI–Oracle about US$13.3 million; Nscale–Anthropic about US$16 million (six years); all per MW per year | Five to six years, 20% to 30% prepaid | Press releases, filings and reporting; calculated by SecondSource |
| CoreWeave company-wide average | About US$6.9 million to US$8.2 million per MW per year | All contracts | SecondSource's rough calculation |
GB200 is NVIDIA's newer-generation chip. The table mixes generations. Pay-as-you-go and one-year prices are for the H100. The short contract and the cancellable order are converted on the assumption of GB200s. The long contracts come only as per-MW figures. The multiples compare per-MW annual figures, not the same card at the same moment. Counting the cancellable big orders, the short end runs about 3 to 6 times the long contracts. SemiAnalysis estimates that cancellable contracts of this kind earn three to four times the revenue per MW of peers. On October 13 the Wall Street Journal, citing SemiAnalysis, said one-year H100 prices had risen about 60% over the past year. The original calculation behind the 60% hasn't been reviewed, so its period is unclear; that period is not the same stretch as the October 2025 to March 2026 rise in the table.
How the per-MW figure for long contracts is calculated. The five long contracts are IREN's US$3.4 billion with NVIDIA for about 60 MW (press release); IREN's US$9.7 billion with Microsoft for 200 MW; Nebius's US$17.4 billion with Microsoft for up to 300 MW; the US$44.6 billion that Nscale, another company renting out GPU capacity, has with Anthropic for 460 MW over six years; and one between OpenAI and Oracle. Total contract value is divided by years, then by announced capacity. Capacity is measured inconsistently. IREN's 200 MW is the power the servers themselves draw. Nebius's 300 MW is the facility's design capacity, with only 50 MW energized so far (Epoch AI's data-center directory). Nscale's 460 MW comes online only at the end of 2027. So only a range is given. The OpenAI–Oracle terms come from reporting that cites anonymous people. A podcast host has also relayed a secondhand figure of about US$24 million to US$25 million per MW for long contracts. The source and method behind that figure are unclear, so the figure serves only as a contrary reference.
Converting the short-contract price to a price per GPU per hour. A GB200 rack holds 72 GPUs, and third-party technical write-ups put a fully loaded rack at 120 to 132 kW. So one MW of server power holds about 545 to 600 GPUs, and US$40 million per MW per year works out to about US$7.6 to US$8.4 per GPU per hour. For the H100, an eight-GPU machine draws about 10 kW, so one MW holds about 800 GPUs, at about US$5.8 per hour. If the presentation's power figure includes cooling and networking, fewer chips fit per MW and the hourly price is higher, still in the same layer. CoreWeave's list prices are US$6.16 for the H100, US$8.60 for the B200 and US$10.50 for the GB200, so the short-contract price lands roughly in the list-price layer. Short contracts are expensive compared with long ones, not compared with list prices. CoreWeave has not said which chip generation the short contracts use, so this passage shows only the order of magnitude.
Why the company-wide average is low. The 10-Q puts contracts not yet fulfilled at US$103.7 billion. Of that, 41% is expected to be recognized as revenue within the 24 months to the end of June 2028, 39% in months 25 to 48, and the rest in months 49 to 78. The 10-Q does not say when each group of contracts was signed or when each ends. SemiAnalysis wrote in April that H100s were being renewed at prices locked in two to three years earlier. An inference provider wrote in October 2024 that the market had flipped from a shortage at US$8 an hour to a glut at US$2. If active power is facility power including cooling, 20% to 30% fewer chips fit per MW than under the basis the presentation used for short contracts, and the ratio drops a further notch. Active power grew by nearly 500 MW during the quarter; using the quarter's average of about 1.25 GW instead, the company-wide average is about US$8.2 million per MW per year.
Details of the public index. Each week getdeploying records every provider's pay-as-you-go listed price. getdeploying takes a median for each provider and then a median across providers, one vote per provider, leaving out reserved and spot prices. SecondSource recomputed October 12 against September 14 from getdeploying's public weekly data: the median change across the 26 models is 8.6%, and against October 13, 2025 it is 18.2%. Nebius's new prices from October 1 were reported by the press by September 17 (Investing.com): the H100 from US$3.85 to US$4.50, the H200 from US$4.50 to US$5.40, the B200 from US$7.15 to US$8.50 and the B300 from US$7.85 to US$9.50. Several outlets called it the second increase in three months. All five data-center models in the index rose between September 14 and October 12: the H100 from US$3.34 to US$3.51, the H200 from US$4.44 to US$4.86, the B200 from US$6.52 to US$7.99, the B300 from US$7.87 to US$8.99 and the A100 from US$1.75 to US$1.82. The rise is uneven across generations: the H100 is up 5% over four weeks, the B200 up 23%. Compute Desk, another index provider, builds its index from completed transactions. Compute Desk says the B300 pay-as-you-go price rose 17 days in a row to a record on October 15, at about US$7 to US$10 an hour, about 64% above November 2025. That account comes from a single secondhand source. The September 18 call's claim that the public index can't see the tightness narrows to this: the index can't see increases in contract prices. The September 18 call also said that a near-double-digit quarterly rise in the public index in the fourth quarter would mean the two measures had converged. A 9% rise over four weeks is already close, but what rose is the listed price itself.
The big-cloud layer. On getdeploying's listed medians, the H100 costs US$7.89 at big clouds and US$4.50 at specialist GPU clouds, 75% higher. The H200 is 101% higher and the B200 68% higher. Silicon Data's head of research said in late September that big clouds often charge two to three times or more what specialist GPU clouds charge, because other services are bundled in. For that reason Silicon Data lists big clouds separately and keeps them out of its index. Silicon Data's late-July report said the gap narrowed from about 250% in early 2025 to about 120% in the third quarter. Tightness at this layer shows up as customers who can't get capacity, not in list prices. Amazon CEO Andy Jassy said in late July that Amazon had raised 2026 capital spending to about US$220 billion and still could not meet this year's demand, and that next year would be the same (Fortune).
Rental futures. CME, the Chicago futures exchange, has announced plans to list futures on Silicon Data's H100 and B200 rental indexes, pending approval from the CFTC, the US commodity futures regulator. ICE and Ornn are also pushing GPU rental futures. These indexes measure the pay-as-you-go and short-term layer at specialist GPU clouds; big clouds are listed separately, and big orders are signed off-exchange. Futures can help GPU owners lock in future rental prices, but cannot show the compute cost AI model companies actually pay under long contracts.
Does the market expect prices to fall? In mid-July Silicon Data published H100 prices by term (original): spot about US$2.72 an hour, a three-year lock about US$2.38, about 13% lower. That gap can be read as the market expecting spot to fall within three years, or simply as the discount for a long commitment. With only the July reading, the two readings can't be separated.
Other readings to watch. (1) getdeploying's four-week readings for November and December, and whether Nebius raises prices a third time. If the four-week reading falls back below 3% with no new list-price change, the reading that the public index moves only when sellers change list prices is supported. If the index keeps rising close to double digits a month, and the rise comes from most providers, prices are rising across the board. (2) If Silicon Data's term prices flip so that longer locks cost more, the reading that the market expects spot to fall no longer holds. (3) Any GPU rental company disclosing the share of short contracts among new signings. The September 18 call said the premium sits in "a small slice"; how small, no one has made public. (4) New undelivered contract value, which the industry calls backlog, divided by new contracted power. Backlog rose to US$104.2 billion in the second quarter and added another US$25 billion early in the third, while contracted power rose from 3.7 GW to 4.2 GW. Without the contract years, this ratio can't be turned into an annual figure, so only its direction can be read.
Placing this on a trend SecondSource tracks. SecondSource maps the arguments over whether the world's compute investment, upward of a trillion dollars a year, is worth it in the tree below. The arguments fall into three camps. One camp says too little is being bought. One says AI's value has not yet turned into revenue anyone pays for. One says cash flow and borrowing will decide the outcome first.
Open ?
Where this sits on this publication's map: this piece's evidence sits on the supply side: newly signed contract prices are rising, and long-contract terms are getting tougher. Rental prices that hold up improve the payback prospects of companies that borrowed to build data centers, but new prices reach revenue only as old contracts expire. The original call on the three-camp debate is unchanged. What this piece adds is that the claim "rental prices are holding up" first has to say which kind of price it means.
What this piece checked. The material is SEC filings and earnings-call transcripts, the website price lists of two GPU rental companies, getdeploying's and Silicon Data's index pages and free datasets, the companies' contract press releases, the free section of SemiAnalysis and a few relays in the financial press. Where this piece says something is absent or the only one of its kind, that holds within this scope only.
Sources
These are the original documents and data pages read directly for this piece; where only a secondhand account was available, the text says so.
- CoreWeave second-quarter quarterly report (10-Q, SEC): Form 10-Q for the quarter ended June 30, 2026
- CoreWeave convertible-note investor presentation (8-K exhibit, SEC): Investor Presentation September 2026
- CoreWeave second-quarter earnings call transcript (The Motley Fool): CoreWeave Q2 2026 Earnings Call Transcript
- CoreWeave second-quarter results press release: CoreWeave Reports Strong Second Quarter 2026 Results
- CoreWeave pricing page: coreweave.com/pricing
- Nebius pricing page: nebius.com/prices
- getdeploying GPU price index: GPU Price Trends, H100 prices by provider
- Silicon Data: H100 rental index, GPU Futures (2026-07-17)
- SemiAnalysis (free section): The Great GPU Shortage (2026-04-02)
- IREN press release (via Nasdaq): IREN's US$3.4 billion five-year contract with NVIDIA
- Epoch AI data-center directory: Microsoft–Nebius New Jersey
- Investing.com: Nebius to increase prices for Nvidia GPU resources from October (2026-09-17)
- Fortune: Andy Jassy on Amazon capex and demand (2026-07-30)
Written from the same research and judgments as the Traditional Chinese edition. Sources are linked; we distinguish original documents from reporting and mark what we could not verify.