Today
Bloomberg says data center debt is getting costlier
Bloomberg reports that even top-rated AI data center debt is getting more expensive, and 30-plus financiers say raising money is harder, while issuance is still about level with last year
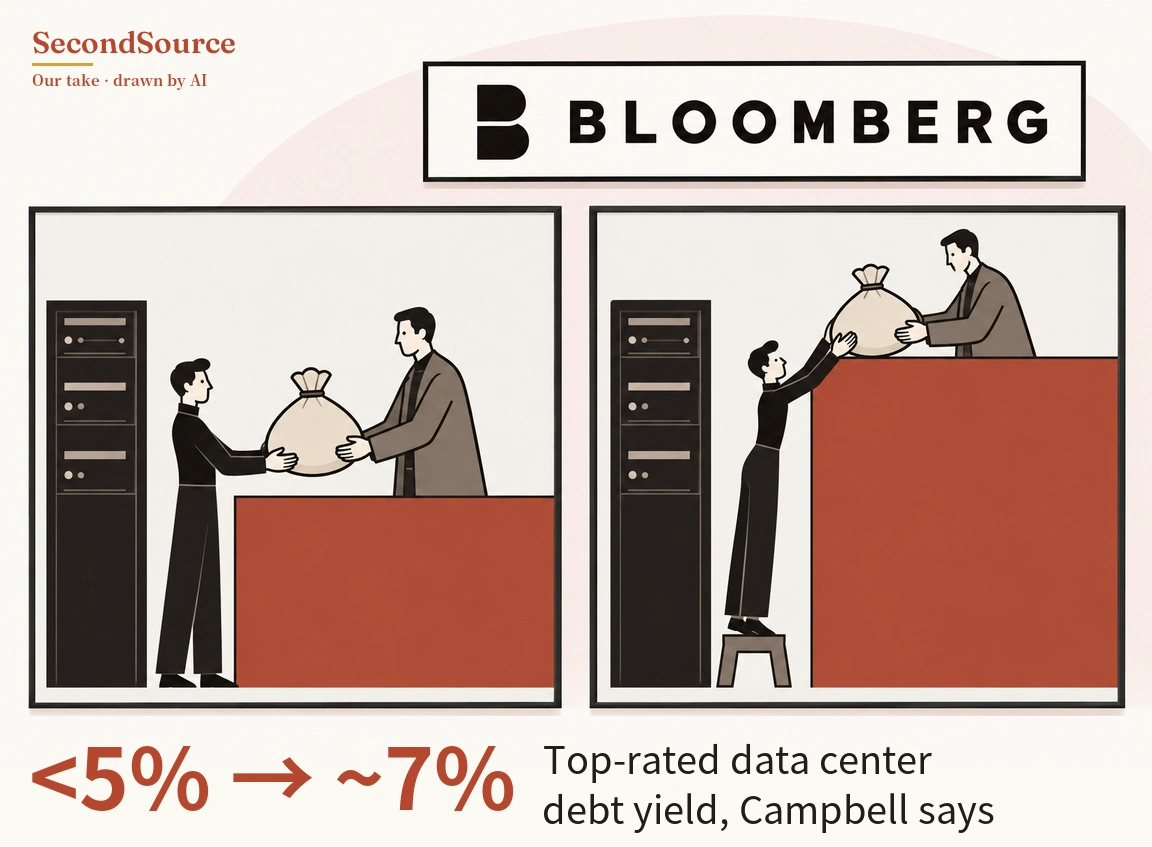
Why it matters: Our inference: lenders are charging more and tightening terms rather than refusing data center borrowers, so companies planning new data centers should budget for costlier debt, not for no debt.
Bloomberg published an original report on October 28 based on interviews with more than 30 bankers, asset managers and private-equity executives involved in data center finance.
Yields on data center debt have risen this year. A yield is the annual return a bond buyer demands, so a higher yield means the borrower pays more interest. Carolyn Campbell, an asset-backed securities strategist at Morgan Stanley, says yields on top-rated data center debt were below 5% at the start of the year, are now close to 7%, and issuance gets noticeably harder near 8%. Campbell's figure of nearly 7% is where comparable bonds trade in the market now; the report gives no rate for newly issued bonds. Asset-backed securitization packages data center rental income into bonds sold to investors. Bloomberg's own data show at least 18 data center financings yielding double digits in the lower-rated high-yield bond and leveraged loan markets. Another example is Volta Infrastructure, a compute rental company. Its US$5 billion syndicated loan found buyers only after JPMorgan and Goldman Sachs cut the price, which pushed the yield past 11% (Bloomberg, 2026-10-28; syndicated full text of the same report). US Treasury yields rose over the same period: the Federal Reserve's H.15 release shows the 5-year Treasury yield at 4.19% at the end of June and 5.09% at the end of September (Federal Reserve H.15). How much of the nearly 7% is extra risk compensation demanded by lenders can't be separated out from the report's figures.
Lenders say they are near their limits, and buyers have started reading the terms. The head of technology, media and telecom lending at a large European bank says lending to the sector is near its ceiling. A survey by the consultancy Willis Towers Watson shows some insurers reached or neared their data center exposure limits months ago. KKR avoids data centers in remote locations, Carlyle has turned down several deals, and Impax is underweight. One hedge fund turned down a deal because the tenant could walk away if construction ran more than three months late, and law firms have seen clauses allowing exit after 180 days. Citadel analyst Tucker Roberts says the difficulty in placing this much debt may no longer be finding investment-grade backers but finding real buyers willing to absorb more risk. Backers here means the cloud giants or chipmakers that support these loans with guarantees or long-term contracts. Roberts says these risks used to sit with the same small group of backers, but he doesn't predict an immediate credit crunch. All of this comes from the same report.
Even so, data center issuance has held up. Campbell says data center issuance in the asset-backed and commercial mortgage-backed securities markets is about US$22 billion so far this year, just keeping pace with last year; the report doesn't say whether the comparison is with the same period last year or the full year. That figure covers only those two markets, not corporate bonds, project loans or private credit.
Not proven yet: most of the 30-plus interviewees are anonymous, and "near the limit" is the reporter's synthesis How we checked →
Investor note: Musk said on October 25 that the debt market is nearly closed to operators without independent revenue. What this Bloomberg report supports is borrowing getting more expensive and lenders getting choosier; with data center securitization issuance still about level with last year, the report doesn't support "nearly closed."
Next to watch: fourth-quarter data center debt issuance, and whether any named financing is pulled. If fourth-quarter data center securitization issuance falls below the same period last year, or a named deal is pulled, the reading that lenders are charging more rather than refusing has to change. Bloomberg's report also says that if the cloud giants' profit growth keeps up with their capital spending, credit markets may again fund speculative projects.
Source and checks
This item ran in the brief of Oct 29, 2026, alongside 16 other items. How we checked it, the quote checks and what was still missing that day are on that issue's How we checked page.
Cite this item
SecondSource (2026). "Bloomberg says data center debt is getting costlier." https://secondsource.io/en/news/2026-10-29-2/. Accessed access date.